AAPL GEX | Apple Inc Real-Time Gamma Exposure & Intraday Levels
Monitor real-time AAPL GEX, 0DTE dollar net gamma exposure, Call Walls, Put Walls, and Zero Gamma Flip thresholds. Quantify how options market maker delta hedging obligations dictate intraday AAPL share pinning and volatility.
Apple Inc · Net GEX & Volatility Boundaries
Underlying AAPL
Per 1% Move
Primary Overhead Resistance
Primary Downside Support
Regime Transition Threshold
| Metric Level | AAPL Strike | Distance from Spot | Market Maker Role | Volatility Impact |
|---|---|---|---|---|
| AAPL Call Wall | $350.00 | +9.86 pts (+2.90%) | Heavy Call Open Interest Pin / Major Resistance | Dealers Short Calls / Damping Upward Surges |
| AAPL Spot Price | $340.14 | 0.00 pts (Current) | Underlying Apple Inc Cash Value | Mean-Reverting Intraday Flow |
| AAPL Zero Gamma Flip | $313.55 | -26.59 pts (-7.82%) | Long to Short Gamma Transition Threshold | Volatility Shift Zone (Long GEX → Short GEX) |
| AAPL Put Wall | $340.00 | -0.14 pts (-0.04%) | Heavy Put Open Interest Floor / Primary Support | Dealers Long Puts / Buying Index Futures on Dips |
| 0DTE Intraday Gamma | PRO EXCLUSIVE | Sub-second live streaming | Real-time 0DTE Call/Put Wall migrations & intraday gamma flip alerts | Unlock in Pro ($99/mo) |
AAPL Pre-Market Institutional Outlook & Plain-English Interpretation
With AAPL spot trading at $340.14 (above the Zero Gamma Flip of $313.55), options market makers operate in a Positive Gamma Regime. In this state, dealers are mathematically required to trade counter-trend: buying underlying futures on dips and selling into rallies. This systematic hedging suppresses realized volatility, pinning price action between structural boundaries.
Primary overhead resistance is anchored at the AAPL Call Wall ($350.00), representing a distance of +9.86 pts (+2.90%). Primary institutional downside support rests at the AAPL Put Wall ($340.00), located -0.14 pts (-0.04%) below current price.
Mean-reversion fades at Put Wall touches offer favorable 3:1+ risk-to-reward setups, while rallies into the Call Wall face persistent dealer selling pressure.
Understanding Real-Time AAPL Gamma Exposure (AAPL GEX)
What is AAPL Gamma Exposure (AAPL GEX)?
AAPL Gamma Exposure (AAPL GEX) measures how Apple options market maker positions force real-time delta hedging. Positive AAPL GEX suppresses stock volatility by compelling dealers to buy dips and sell rallies, while negative GEX accelerates downside selling pressure.
In financial options markets, AAPL gamma exposure represents the mathematical rate of change in options market maker deltas relative to underlying price shifts in AAPL stock. Because options dealers maintain delta-neutral books, any movement in Apple stock forces market makers to dynamically buy or sell shares or futures to remain hedged.
When institutional and retail traders purchase call options, market makers take the opposing side by shorting calls and buying underlying shares to hedge delta. As AAPL stock rises, the call delta increases, forcing dealers to buy additional shares to remain neutral. This programmatic feedback loop is at the heart of modern market microstructure and makes the GEX Horizon Real-Time Gamma Dashboard an indispensable tool for active equity traders.
Live AAPL Net GEX Current Value & 0DTE Breakdown
Explore real-time net dollar gamma levels across all expirations, zero-day contracts, and monthly settlement cycles using our interactive Gamma Heatmaps and Gamma Histograms.
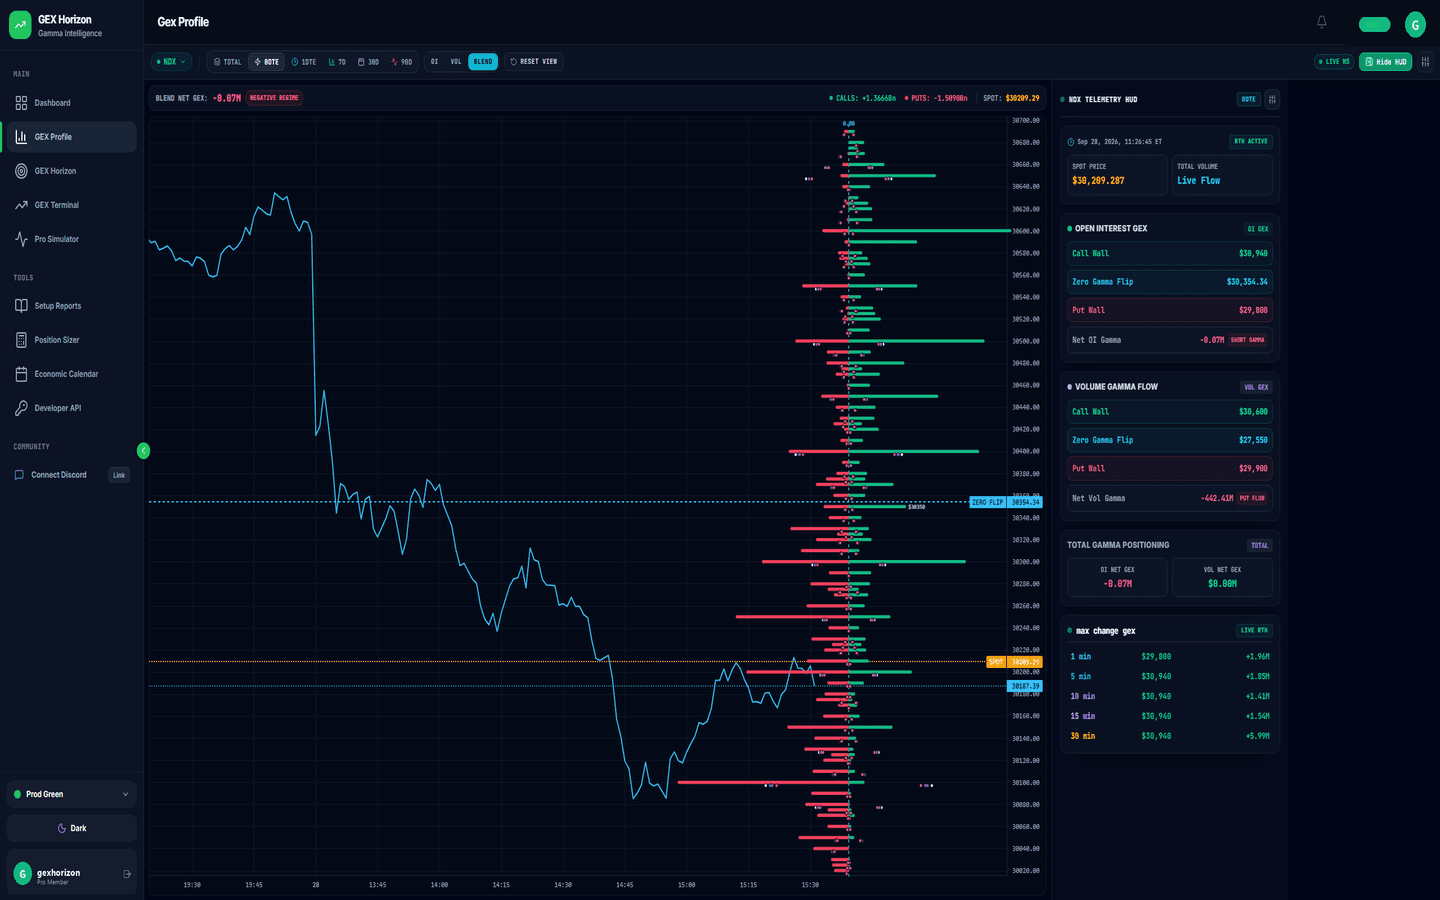
0DTE AAPL Net GEX Current Value vs All Expirations
Zero Days to Expiration (0DTE) AAPL options attract immense retail day-trading volume. Because 0DTE options possess extremely high gamma decay, rapid call buying surges can cause the AAPL net GEX current value to shift rapidly within minutes during market hours, generating dramatic intraday runs.
Single Stock Option Leverage vs ETF Basket Index Options
Apple options carry unique characteristics compared to index options like SPX or options like SPY. AAPL options are highly leveraged single-stock derivatives with physical share settlement. Because retail call buying is highly concentrated in AAPL, dealers holding short calls are exposed to massive directional delta risk, which often triggers explosive feedback loops (gamma squeezes).
AAPL Call Wall, Put Wall & Zero Gamma Flip Matrix
Options market makers dictate the boundaries of daily volatility. The three primary structural anchors are the Call Wall, the Put Wall, and the Zero Gamma Flip.
By multiplying strike-level gamma by total open interest (verified daily via the Options Clearing Corporation (OCC)) and scaling by stock spot value, GEX Horizon calculates the dollar gamma market makers must rebalance for every 1% move in the stock.
How Dealers Rebalance Delta at the AAPL Call Wall and Put Wall
The AAPL Call Wall serves as formidable resistance or a magnetic draw. When dealers are short calls, they must buy AAPL shares as the price approaches the wall strike to cover delta. The AAPL Put Wall represents the strike price with the largest negative gamma concentration, serving as critical support where market maker hedging cushions downside sell-offs.
Identifying Volatility Suppression vs Volatility Expansion Regimes in AAPL
Trading above the AAPL Zero Gamma Flip level places the market in a positive gamma regime. Market makers hedge by buying dips and selling rallies, suppressing volatility. Conversely, falling below the flip level triggers a negative gamma regime. Market makers are forced to sell into declines and buy into rallies, accelerating volatility and widening intraday trading ranges.
Institutional AAPL Intraday Trading Playbook: Executing GEX Setups
Professional derivatives desks leverage strike-level dealer hedging obligations to identify intraday momentum surges, pinpoint exhaustion boundaries, and execute tactical single-stock mega-cap exposures. Here are three primary execution setups tailored to AAPL market microstructure.
Call Wall & Put Wall Boundary Fades
When AAPL trades above its Zero Gamma Flip line, dealers operate in positive gamma. Approaching the Call Wall, market makers must aggressively sell AAPL shares to neutralize expanding long deltas, damping further upside momentum unless overwhelmed by institutional volume.
Zero Gamma Flip Regime Transition
Breaching the AAPL Zero Gamma Flip alters market maker behavior instantly. Below the flip, dealers must sell into declines and buy into rallies to remain delta neutral, accelerating downward market velocity.
Friday Weekly Expiration Strike Pinning
During the final two hours of weekly expiration Fridays, heavy open interest option contracts undergo severe time decay. Options desks managing heavy near-the-money volume continuously re-hedge, creating a powerful magnetic pull toward peak open interest strikes.
Higher-Order Derivatives Dynamics: How Vanna and Charm Alter Dealer Hedging in AAPL
Standard gamma exposure measures dealer hedging adjustments driven solely by underlying stock price movement. However, active market makers continuously rebalance deltas in response to changes in implied volatility (Vanna) and the passage of time (Charm).
The Implied Volatility Feedback Loop
Vanna measures the rate of change in option delta relative to shifts in implied volatility. Because institutional investors systematically write calls and hold puts across broad portfolios, dealer books reflect balanced multi-strike exposures in Apple shares.
When market-wide implied volatility compresses during stable sessions, the deltas of protective dealer puts contract. To remain neutral, market makers purchase Apple shares in cash markets, providing a persistent structural floor that reinforces upside drift.
The Weekly Time Decay Unwind
Charm measures the rate of change in option delta with the passage of time. With weekly option expiries every Friday, time decay accelerates sharply throughout Thursday and Friday trading sessions.
As expiration approaches, the deltas of out-of-the-money options erode toward zero. Market makers holding hedges against these decaying contracts must systematically unwind their positions. On sessions with elevated out-of-the-money put open interest, Charm decay generates predictable afternoon buying pressure into session settlement.
Market Maker Delta Hedging Mechanics in AAPL Options
Options market maker delta hedging is the core transmission mechanism linking derivative flow to cash market price actions.
Institutional traders utilize this mathematical metric to anticipate liquidity buffers and market maker order flow toxicity. For an in-depth mathematical walkthrough, consult our full guide on How to Calculate and Interpret Gamma Exposure.
Frequently Asked Questions: AAPL GEX & Intraday Levels
Essential answers regarding Apple Inc options gamma exposure, dealer delta hedging, and intraday level interpretation.