Loading Market Analytics
Streaming institutional gamma levels and market structure...
Track real-time options volume profiles, strike GEX distribution bars, and CBOE market maker hedging requirements for **MSFT**.
Underlying MSFT
Per 1% Move
Primary Overhead Resistance
Primary Downside Support
Regime Transition Threshold
| Metric Level | MSFT Strike | Distance from Spot | Market Maker Role | Volatility Impact |
|---|---|---|---|---|
| MSFT Call Wall | $510.00 | +10.00 pts (+2.00%) | Heavy Call Open Interest Pin / Major Resistance | Dealers Short Calls / Damping Upward Surges |
| MSFT Spot Price | $500.00 | 0.00 pts (Current) | Underlying MSFT Equity / ETF Cash Value | Mean-Reverting Intraday Flow |
| MSFT Zero Gamma Flip | $497.00 | -3.00 pts (-0.60%) | Long to Short Gamma Transition Threshold | Volatility Shift Zone (Long GEX → Short GEX) |
| MSFT Put Wall | $490.00 | -10.00 pts (-2.00%) | Heavy Put Open Interest Floor / Primary Support | Dealers Long Puts / Buying Index Futures on Dips |
| 0DTE Intraday Gamma | PRO EXCLUSIVE | Sub-second live streaming | Real-time 0DTE Call/Put Wall migrations & intraday gamma flip alerts | Unlock in Pro ($99/mo) |
With MSFT spot trading at $500.00 (above the Zero Gamma Flip of $497.00), options market makers operate in a Positive Gamma Regime. In this state, dealers are mathematically required to trade counter-trend: buying underlying futures on dips and selling into rallies. This systematic hedging suppresses realized volatility, pinning price action between structural boundaries.
Primary overhead resistance is anchored at the MSFT Call Wall ($510.00), representing a distance of +10.00 pts (+2.00%). Primary institutional downside support rests at the MSFT Put Wall ($490.00), located -10.00 pts (-2.00%) below current price.
Mean-reversion fades at Put Wall touches offer favorable 3:1+ risk-to-reward setups, while rallies into the Call Wall face persistent dealer selling pressure.
Explore real-time net dollar gamma levels across all expirations, zero-day contracts, and monthly settlement cycles.
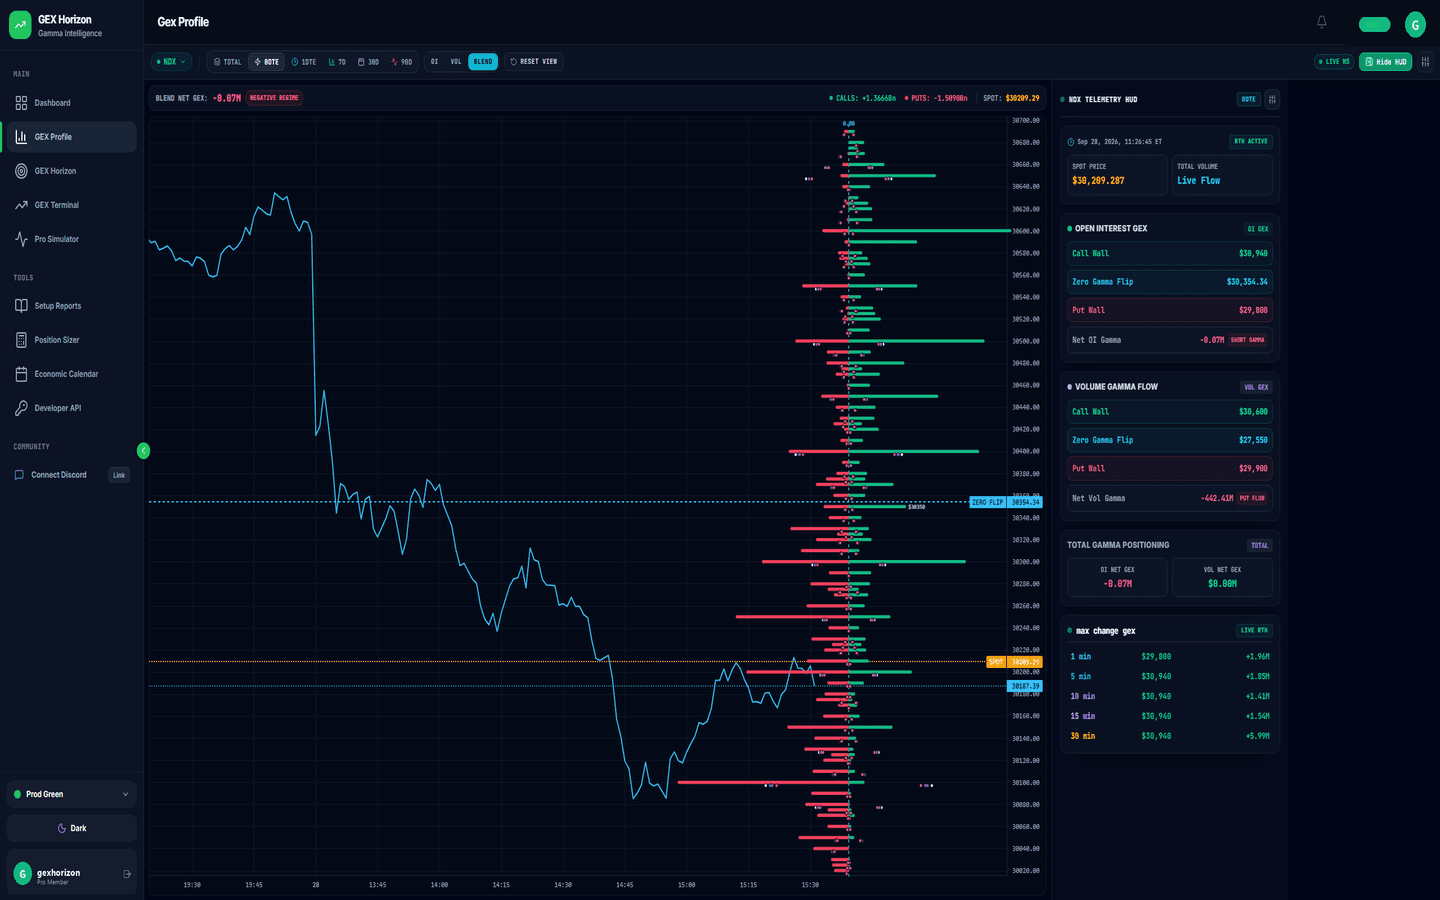
The options derivatives market for MSFT represents a key indicator of institutional positioning and retail sentiment. On any given trading day, thousands of call and put options contracts are exchanged across various expirations. For options market makers who write these contracts, managing inventory risk is a continuous task. Dealer delta hedging in MSFT options directly influences intraday price action, volatility, and trend sustainability.
When a trader buys a call option on MSFT, the dealer who sold that contract becomes short delta. To hedge this exposure and remain delta-neutral, the dealer must purchase shares of the underlying MSFT stock in the open market. As the price of MSFT moves, the delta of the option contract changes, requiring the dealer to dynamically adjust their hedge by buying or selling shares. This feedback loop is known as dealer gamma hedging, and it dictates the daily trading boundaries.
In the MSFT options flow, three key levels determine institutional support and resistance:
With the rise of 0DTE (Zero Days to Expiration) option contracts, intraday swings in MSFT are increasingly driven by short-term delta rebalancing. Large blocks of call or put options bought in the morning can shift the MSFT net GEX value by millions of dollars, leading to rapid trend accelerations or sudden price pins at key strikes. Monitoring these volatility shifts allows derivatives traders to identify short-term reversals and momentum breakouts.